Imagine a freelancer in Nairobi finishing work for a client thousands of kilometres away. The payment lands quickly in a dollar stablecoin. On paper, the hard part is over.
Then ordinary life begins.
Rent is priced in shillings. A supplier wants money in the form they already understand. The landlord does not care that settlement happened on-chain.
This is the contradiction inside borderless finance: money can become globally mobile before it becomes locally useful.
The next serious contest may not be who moves value fastest, but who makes global money behave naturally once it arrives somewhere specific.
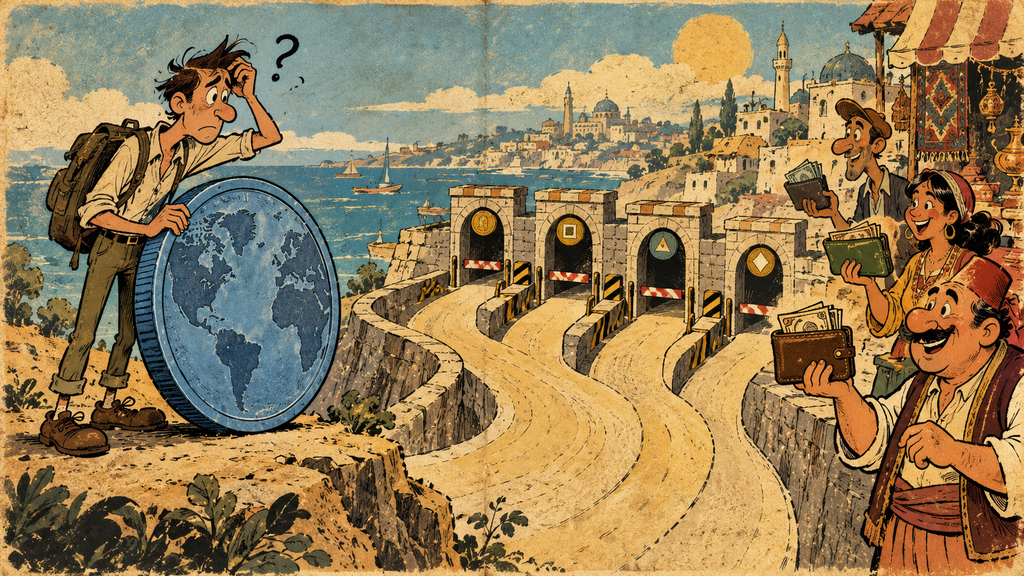
Borderless Has Met the Border
In the United Arab Emirates, Network International began an in store pilot allowing customers to pay with an AED backed stablecoin through existing merchant terminals. The revealing detail is not merely that a stablecoin reached checkout. It is that local digital money was plugged into familiar retail hardware. Network International
In Kenya, Minisend is expanding a stablecoin settlement service designed to let users receive assets such as USDC and USDT and settle them through local financial channels. Citizen Digital
People live locally while earning, selling and communicating globally.
Habit Is Stronger Than Technology
Stablecoins inherit some of the dollar’s appeal: familiarity, liquidity and usefulness in international commerce.
UPI processed about 24.5 billion transactions in August, according to NPCI. Reuters reported that India is preparing infrastructure that could allow artificial intelligence agents to make permitted routine payments through UPI, with spending limits, identity checks and liability rules. NPCI
New technology is not replacing the local rail. It is learning to use it.
Crypto once imagined adoption as people leaving old systems. Increasingly, successful products look more like translators between systems.
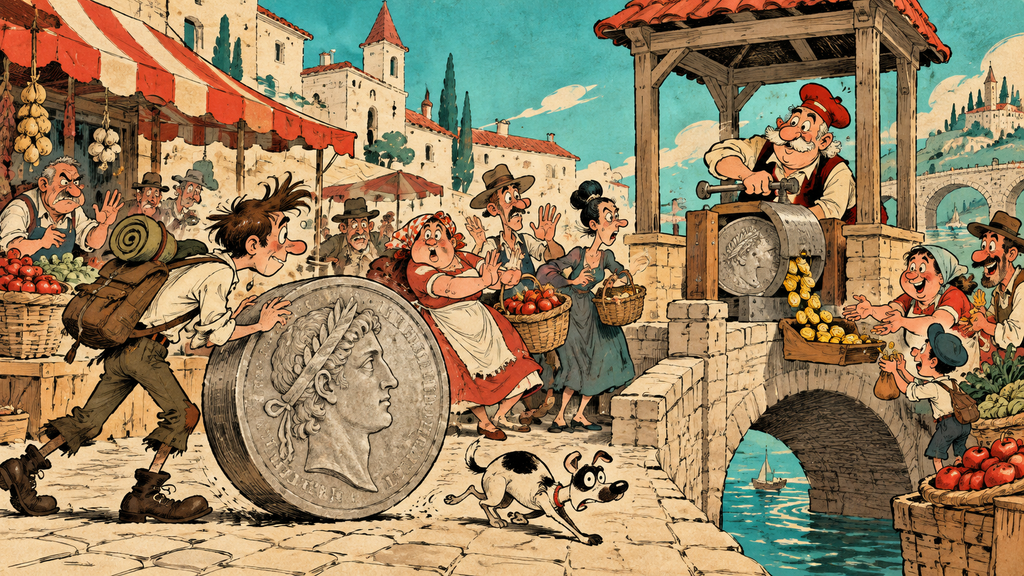
Payments Are Social Before They Are Technical
People use what merchants accept, what friends recommend and what they believe will still work tomorrow.
A payment method becomes credible when it repeatedly survives ordinary life.
A stablecoin working at a merchant terminal says something different from a white paper promising future utility. A friend receiving money successfully says more than an advertisement about speed.
Technically superior money can lose to familiar money when familiar money carries stronger social proof.
Visa offers another clue. More than 160 stablecoin linked card programs were live on its network in its fiscal second quarter. Payment volume had risen nearly 200 percent from a year earlier, while stablecoin settlement volume exceeded a 20 billion dollar annualized run rate. Visa
Cards are old infrastructure. Stablecoins are newer infrastructure. Together, digital value borrows an acceptance network people already recognize.
Local Rules Travel With the Money
Translation is not only about currency. It is also about law.
The United Kingdom has finalized major parts of a crypto framework covering financial resilience, stablecoins, market integrity and regulated crypto activities. Its authorization gateway is scheduled to open before the broader regime takes effect later. FCA
A global financial product cannot build one experience and assume geography has disappeared.
Jurisdictions care about custody, identity, reserves, disclosures, sanctions and consumer protection.
The paradox is almost comic. Digital money becomes easier to move across borders while governments become more precise about what must happen when it crosses them.
The valuable layer may therefore be orchestration: knowing which asset, rail, conversion process and compliance rule belongs to which situation.
CFXN Is Really Being Tested at the Edges
CFXN publicly describes a network combining crypto and fiat wallets, exchange functionality, Crypto Pay and borderless transfers in one account. It also says KYC will apply at launch and customer data used for verification will not be resold. CFXN
The opportunity is not simply offering many currencies.
The harder job is making those forms of value useful in context.
For a future Member, success might look boring: receive one asset, convert when necessary, pay in a form the recipient accepts, and understand what happened.
For an investor, the questions are sharper. Can CFXN create reliable local access? Can it manage liquidity across markets? Can compliance expand with distribution? Can complexity disappear without meaningful costs or risks disappearing from view?
Those questions matter more than how many tokens a wallet supports.
The People Left Behind Matter
People without suitable identification, smartphones, reliable connectivity or access to supported financial channels can remain excluded even when the technology is global.
There is also a subtler exclusion: products designed by people who understand crypto for people who understand crypto.
Most customers do not want a lesson in networks before paying an invoice. They want confidence.
A system must explain itself well enough that ordinary people can recommend it without becoming unpaid technical support.
The best adoption story is not, “I finally understood blockchain.”
It is, “I sent the money. It worked.”
Borderless Finance Needs Better Borders
The irony is that borderless finance may succeed by becoming excellent at borders.
Not walls.
Interfaces.
The places where dollars become shillings, tokens become purchases, global networks meet local rules, and unfamiliar technology becomes ordinary habit.
That is where value is created because that is where confusion lives.
For CFXN, the opportunity is to become useful at those interfaces rather than merely present on both sides.
Future Members should watch whether that promise becomes visible in actual markets, supported currencies, costs, protections, and merchant experiences.
Investors should watch whether expansion produces genuine local usage rather than impressive map coverage.
Explore CFXN’s public proposition, examine the terms that apply in your jurisdiction, and watch how the network develops.
The future of money may be global underneath.
The winning experience will probably feel remarkably, surprisingly local.